For Tech & Equity Compensation
When a large share of your pay arrives as company stock, the biggest money decision of your year gets made by a payroll default. We help you make it on purpose: what to hold, what to sell, when, and what each choice costs in tax.
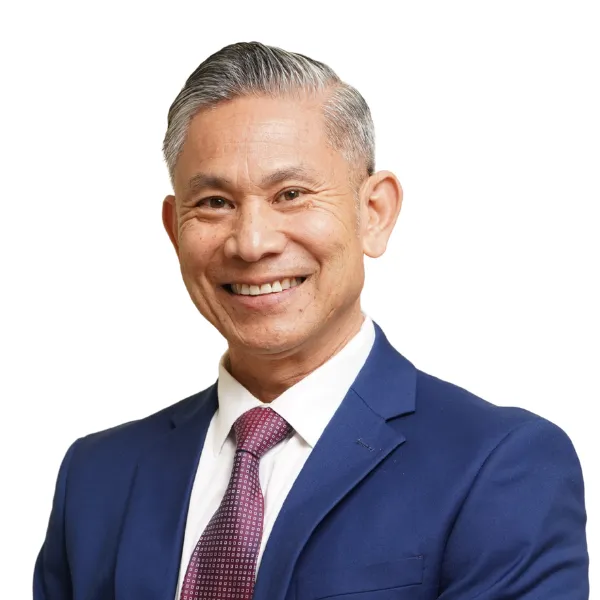
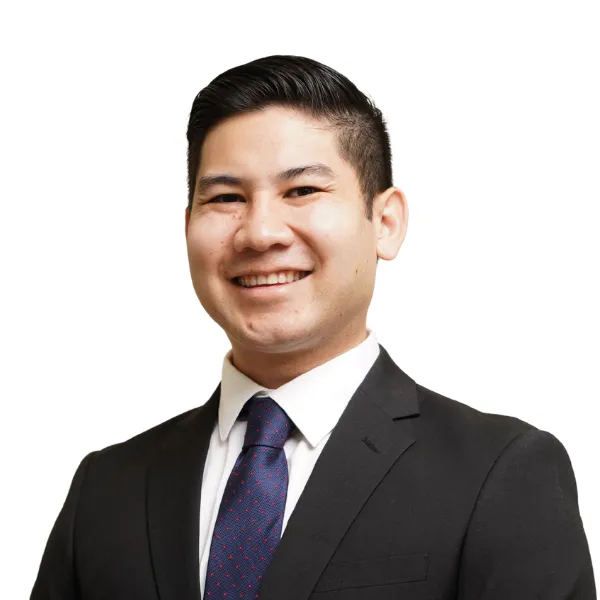
Nasar and Samee Aboubakare
Father and son. You work with both.
Prefer to text? (949) 259-5240
Engineering, product, finance, sales and operations leaders with RSUs vesting every quarter and an ESPP on the side.
Options or RSUs with a tender offer, an IPO or an acquisition on the horizon, and a tax bill that depends on timing.
Accelerated vesting, a cash payout or new acquirer stock, and a short window to make good decisions with it.
Founded or own the company? See Business Owners
Vest-and-hold feels like doing nothing. In practice it is a choice you renew every quarter: to keep putting more of your net worth into the same company that pays your salary. When the stock and the job have a bad year, they tend to have it together.
The usual reason for holding is the tax bill on selling. That bill is real, and it is also something you can plan: across tax years, inside trading windows, at a cost you agree to in advance.
The question worth answering first is how much of your net worth you want riding on one company, and on what schedule you get there. Every vest after that has a rule instead of a debate.
These come up in nearly every equity-heavy plan. Each has a deadline, and the default rarely matches what you would choose.
RSU income is usually withheld at a flat 22% federal rate. If your income puts you in the 32%, 35% or 37% bracket, the difference comes due in April, sometimes with an underpayment penalty, and before state tax.
How much company stock is too much depends on your goals, your timeline and how much of your income already comes from the same company. We set a target and a selling schedule in advance, so each vest isn't a fresh debate.
The ESPP discount and incentive stock options are taxed differently depending on how long you hold and when you sell. Exercising ISOs can trigger the alternative minimum tax, and most of those choices close on December 31.
An acquisition, a tender offer or a job change can accelerate vesting, cash you out, or start a 90-day clock on your options. The planning window is usually short, and it opens before the money arrives.
Timing
Illustrative example
A product manager has $300,000 of RSUs vest this year, on top of a salary that already puts them in the 35% federal bracket. Payroll withholds 22% on the vesting shares, or $66,000. The federal tax on that income is closer to $105,000, so about $39,000 comes due in April, before California tax and any underpayment penalty.
Nothing went wrong here. This is the default working as designed. The planning question is what to do before the next vest: change the withholding, set aside cash from planned sales, or hold less. The right answer depends on the rest of the plan.
Hypothetical example for illustration only. Figures are simplified and rounded, assume all of the RSU income is taxed at the 35% rate, and ignore state tax. Your results will differ. This is general education, not individual tax or investment advice.
Who you'll work with
Every client works with both of us. Nasar founded Sporos and brings the calm perspective and institutional memory behind every plan. Samee trained as a chemical engineer at the University of Michigan and did equity research at a family office before joining the practice, so the analysis behind your plan is precise and the reasoning is written down.
For equity-heavy plans, that means a grant schedule and a tax projection read line by line, and the judgment of someone who has seen concentrated positions through more than one market cycle. We built the practice father and son so your plan always has someone who knows it, for the next 30 years and beyond.
Every relationship starts with a 30-minute conversation about your equity, your timeline and what you want the money to do. From there, people usually take one of two paths.
We run the plan with you: selling schedules, tax planning around every vest and exercise, and the diversified portfolio the stock turns into.
A complete written plan for $3,000, with no assets moved. If you later move to ongoing management, the fee is credited.
How the flat-fee plan worksWe'll tell you on the first call which path fits, including when neither does.
Yes. We meet virtually and work with clients in 15 states: AL, AZ, CA, CO, GA, IL, NJ, NV, NY, OH, OK, OR, PA, TX and WA. Our office is in Huntington Beach if you would rather meet in person.
No. The first call is about where you are and where you want to go. If working together makes sense, we'll say so and explain how. If it doesn't, we'll tell you that too.
No. We start with what you want the stock to do for your plan, then agree on a target and a schedule. Some clients diversify over a few years. Some keep a meaningful position on purpose. Either way, the decision is yours, and it is made in advance.
30 minutes on what you hold, what's coming, and whether we're the right fit to help you plan it.
Prefer to text? (949) 259-5240