For Families Nearing Retirement
In the 5 to 10 years around the last paycheck, the questions change: where the monthly income comes from, what it costs in taxes, and how it holds up in a bad market. We build the plan around the three things a retirement plan has to get right.
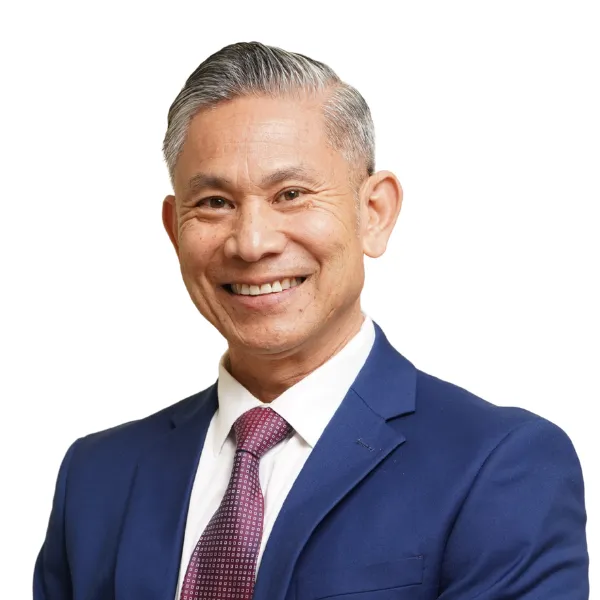
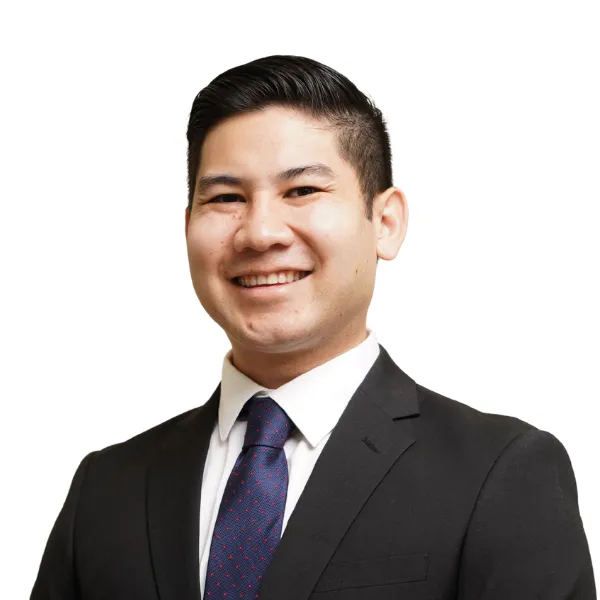
Nasar and Samee Aboubakare
Father and son. You work with both.
Prefer to text? (949) 259-5420
Still working, often at peak income, with a 401(k) that has become the largest asset in the house.
Living on savings for the first time and wanting a plan for the next 30 years of withdrawals.
Lump sum or monthly payments, survivor elections, and company stock in a 401(k) that needs a decision before anything is rolled over.
Still building at a high income? Healthcare Clinicians · Tech & Equity Compensation
For 30 years the job was to save. Retirement asks for a different skill: turning a set of accounts into a paycheck that lasts, taxed as lightly as the rules allow, without selling into a down market to pay the bills.
Most plans are built around the portfolio. Ours starts with the income: what Social Security and any pension cover, how large the gap is, and how to fund that gap safely before anything else is invested for growth.
Plus the timing decisions that sit underneath them. Use these as questions for any advisor you meet, including us.
Social Security and any pension cover part of your monthly need. The gap is what your savings have to produce. We build a protected floor for it first, designed so essential bills don't have to rely on selling investments in a down market.
What you own gets the attention. Where it sits (traditional, Roth or taxable accounts) and the order you draw from each account decide how much of every withdrawal you keep after tax.
Retirement is a 30-year project. We built Sporos father and son so 2 advisors know your plan, and we intend to serve your family for decades.
When to claim, how a spouse's benefit fits, which income raises Medicare premiums, and whether to roll a 401(k) over or leave it. Each has a deadline, and each affects the others.
Timing
Illustrative example
A married couple, both 63, have $1.4M saved, mostly in 401(k)s and individual retirement accounts (IRAs). They spend about $120,000 a year. Social Security at full retirement age will cover roughly $60,000 of it, so the gap their savings must fill is about $60,000 a year.
Most of the planning lives in that gap: how much of it to protect first, which accounts to draw from in which years, and how much to convert to Roth while their bracket is low, before required distributions and Medicare premiums push it up.
Hypothetical example for illustration only. Figures are simplified and rounded, and your results will differ. This is general education, not individual tax or investment advice.
Who you'll work with
Every family works with both of us. Nasar built a private equity firm, then became a financial advisor at a big national firm. He founded Sporos to recommend what fits each family. Samee intends to be here for the long run.
Retirement is a 30-year project. We built the practice father and son because we intend to be there for all of it.
It starts with a 30-minute conversation at no charge. If you want your investments and your plan managed together, the next step is an Analysis Call that walks you through what we found on your current path. If planning on its own fits, you choose your plan on that first call, and your full retirement income plan is delivered at your 90-day meeting.
Your portfolio, income plan, withdrawals, tax strategy, and Social Security and Medicare timing, managed together and adjusted every year. A percentage of the assets we manage, which steps down as your assets grow.
See how we workWe build your retirement income plan and keep it current every year, while you manage your own investments. Income Plan or Advanced, each one flat monthly fee that starts with a plan build. Prefer a one-time plan? The One-Time Retirement Plan is a complete written plan with no monthly fee.
See how we workWe'll tell you on the first call which path fits, including when neither does.
Yes. We meet virtually and work with clients in 15 states: AL, AZ, CA, CO, GA, IL, NJ, NV, NY, OH, OK, OR, PA, TX and WA. Our office is in Huntington Beach if you would rather meet in person.
No. The first call is about where you are and where you want to go. If working together makes sense, we'll say so and explain how. If it doesn't, we'll tell you that too.
Sometimes. It depends on the plan's investment options and costs, whether you hold company stock, your age when you leave, and how you plan to draw income. We look at it case by case, and sometimes the right answer is to leave it where it is.
30 minutes on where you are, when you want to stop, and whether we're the right fit to help you get there.
Prefer to text? (949) 259-5420