For Healthcare Clinicians
Dropping call, going to 4 days, picking up 1099 shifts, owning a practice. For most clinicians we work with, the goal behind the money is control over the work. Each of those moves changes your taxes, your retirement plans and your insurance at once, and we plan for it before it happens.
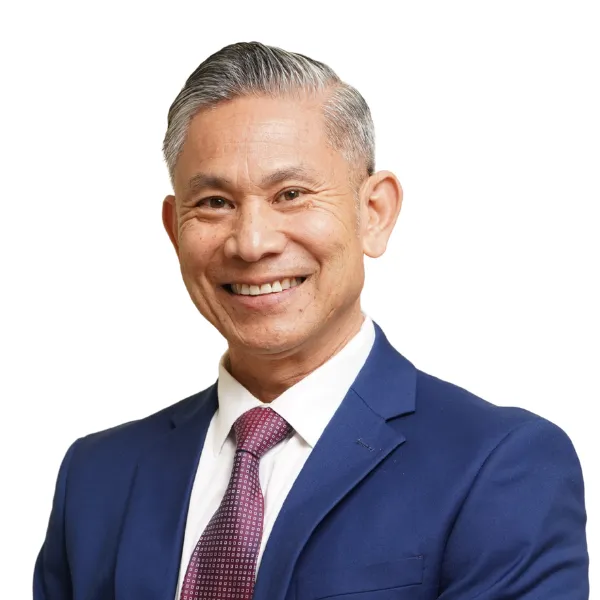
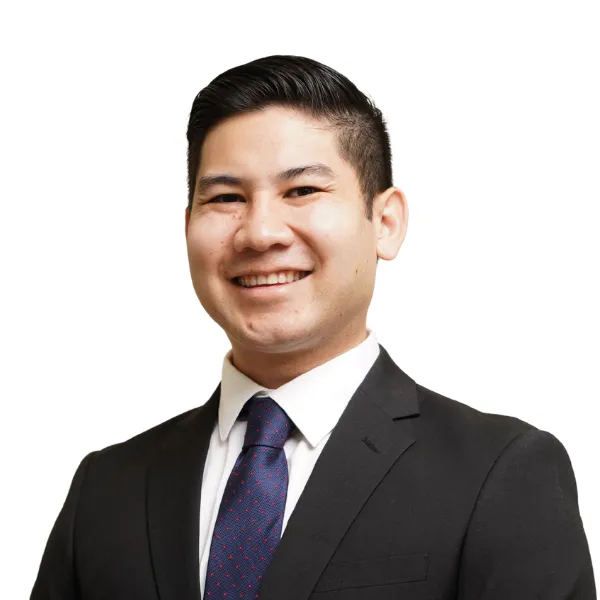
Nasar and Samee Aboubakare
Father and son. You work with both.
Prefer to text? (949) 259-5240
W-2, 1099, or both. Often the highest earners in the building, with the most structure to get right.
Hospital, retail or industry, frequently with a per diem job on the side and loans from a doctorate.
Including clinicians weighing practice ownership, telehealth across state lines, or a move to independent work.
Within 10 years of retiring? Start with Families Nearing Retirement
By the time real income shows up, most clinicians are 28 to 35 and have been deferring since 18. Then the decisions arrive all at once: a benefits portal on day one, a second employer's plan, a loan repayment program, a 1099 offer. Most of them get made by default and are never revisited.
That says nothing about you. Medicine trains you never to guess, and nobody trained you for this part. The cost shows up slowly: old 401(k)s parked in cash, a disability policy that ends with the job, a forgiveness count that stopped after a job change without anyone telling you.
Good planning starts with one question: what would it take to work the way you want to? Every other decision gets measured against that answer.
These come up in nearly every clinician's plan. Each has a right answer for your situation, and the default is usually the expensive one.
Going 1099 changes how you are taxed, which retirement plans you can open, and which insurance you now carry yourself. Set up well, it opens retirement room a W-2 job never offers. Set up by default, it often shelters nothing.
A base job and a per diem job share one $24,500 employee deferral limit in 2026, and neither payroll office sees the other. Add a 403(b), a 457(b) and accounts left at past hospitals, and many clinicians are running 3 or more plans with no one coordinating them.
For your first 15 years of practice, your ability to work is most of your net worth. Group disability through an employer often caps the benefit, may leave out call and differential pay, and ends when the job does. Knowing exactly what you have is the first step.
Public Service Loan Forgiveness depends on who signs your paycheck. Moving from a nonprofit hospital to a private group, a chain or 1099 work can stop the count, and nothing notifies you. We look at the loans before the job change, while there is still time to plan around them.
Timing
Illustrative example
A CRNA works full time at a hospital and picks up about $60,000 a year of 1099 locum work. Her hospital 403(b) already uses the full $24,500 employee deferral limit for 2026, so she assumes there is no retirement room left for the side income.
There is. Her 1099 work is a small business, and that business can make its own employer contribution to a solo 401(k), roughly 20% of what the work nets. On $60,000, that is close to $12,000 a year of pre-tax savings she was leaving unused, before anyone looks at entity structure or a cash balance plan.
Hypothetical example for illustration only. Figures are simplified and rounded, and your results will differ. This is general education, not individual tax or investment advice; we coordinate the details with your CPA.
Who you'll work with
Every client works with both of us. Nasar founded Sporos and brings the calm perspective and institutional memory behind every plan. Samee trained as a chemical engineer at the University of Michigan and did equity research at a family office before joining the practice, so the analysis behind your plan is precise and the reasoning is written down.
For clinicians, that pairing matters: one of us will model a 1099 move to the dollar, and the other has watched how these decisions play out across a career. We built the practice father and son so your plan always has someone who knows it, for the next 30 years and beyond.
Every relationship starts with a 30-minute conversation about where you are and what you want the work to look like. From there, clinicians usually take one of two paths.
We run the plan with you year by year: taxes, retirement accounts, insurance reviews and the investments, adjusted every time your work changes.
A complete written plan for $3,000, with no assets moved. If you later move to ongoing management, the fee is credited.
How the flat-fee plan worksWe'll tell you on the first call which path fits, including when neither does.
Yes. We meet virtually and work with clients in 15 states: AL, AZ, CA, CO, GA, IL, NJ, NV, NY, OH, OK, OR, PA, TX and WA. Our office is in Huntington Beach if you would rather meet in person.
No. The first call is about where you are and where you want to go. If working together makes sense, we'll say so and explain how. If it doesn't, we'll tell you that too.
Yes. Most of what we do for clinicians touches taxes, so we coordinate directly with your CPA. If you don't have one who works with 1099 clinicians, we can help you find one.
30 minutes on where you are, how you want to work, and whether we're the right fit to help you get there.
Prefer to text? (949) 259-5240