For Business Owners
How you pay yourself, how the business is organized, who could run it without you, and where the proceeds will land all shape what you walk away with. We plan the business and the household as one, years before a sale and long after it.
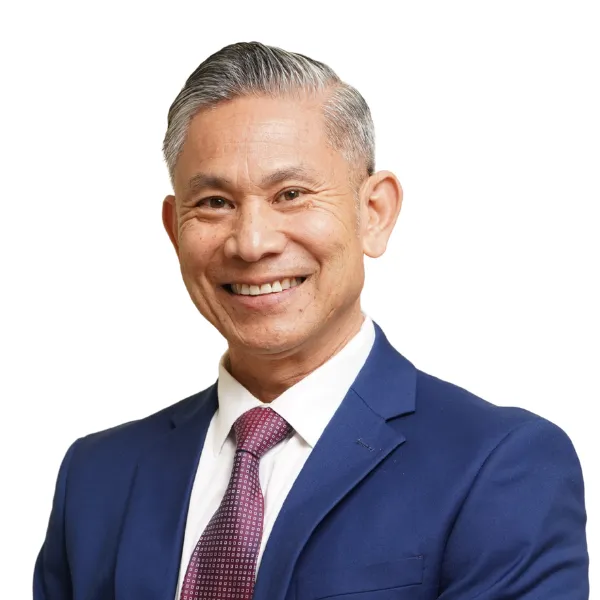
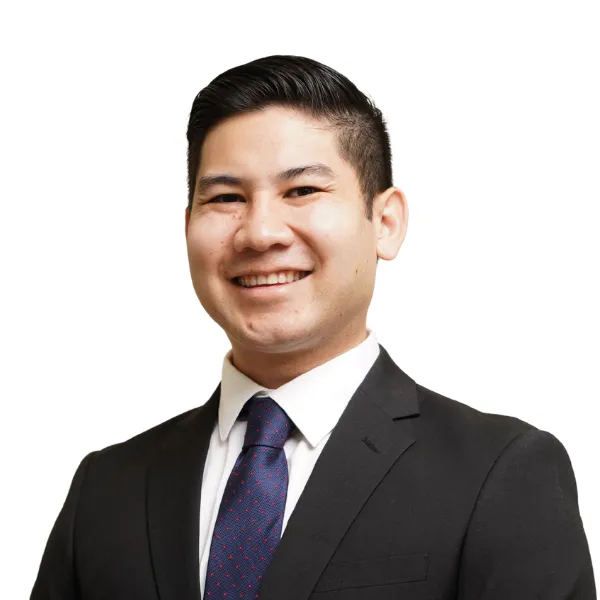
Nasar and Samee Aboubakare
Father and son. You work with both.
Prefer to text? (949) 259-5240
A sale to a buyer, a partner, employees or family in the next 10 years, and a household that will run on the proceeds.
Professional practices and closely held companies where the owner's pay, taxes and retirement are tied up in the business.
Partners, key employees and family who need the business to keep running if something happens to you.
Selling and close to retirement? See Families Nearing Retirement · Offering a 401(k) to your team
Most owners we meet have a well-run company and a thin personal balance sheet beside it. The business funds everything, so the household plan and the business plan are the same plan, and both depend on one sale going well.
The work is to build on both sides at once: take money out of the business as efficiently as possible while you own it, and arrive at a sale with the structure, the records and the household plan already in place.
These come up in nearly every owner's plan, and most of them reward starting early.
How the business is organized and how you pay yourself set your tax rate today and shape what a buyer sees later. We revisit both with your CPA every year.
A 401(k) with profit sharing, or a cash balance plan alongside it, can let an owner set aside and deduct more than $100,000 a year in some cases, depending on age, income and staff.
Asset or stock sale, installment payments, an earnout, a sale to employees or family. Each changes the tax bill and the risk you carry after closing, and some only work if they are set up years ahead.
Buy-sell agreements, key person coverage and a succession plan protect what you've built if you can't run the business tomorrow.
Timing
Illustrative example
The owner of a professional practice, age 55, pays herself a salary and contributes to a standard 401(k). She plans to sell in 8 years and treats the sale as her retirement plan.
Adding a cash balance plan beside the 401(k) could let the practice contribute and deduct more than $100,000 a year toward her retirement, depending on her age, income and the cost of covering staff. Over 8 years, that builds retirement savings that don't depend on what a buyer pays, while lowering taxes in the years she is still working.
Hypothetical example for illustration only. Contribution limits depend on age, compensation, plan design and employee census, and your results will differ. This is general education, not individual tax or investment advice; plan design is coordinated with your CPA and a plan actuary.
Who you'll work with
Every client works with both of us. Nasar founded Sporos after a career at a big national firm and brings private equity experience and an MBA from USC Marshall, so he looks at your company the way a buyer eventually will. Samee trained as a chemical engineer and did equity research at a family office, so the analysis behind your plan is precise and the reasoning is written down.
The plan for the business and the plan for the household change together every year, so it helps to have two people who know both. We built the practice father and son so your plan has someone who knows it for the decades after the sale, too.
It starts with a 30-minute conversation about the business, the household and your timeline. Owners usually work with us on an ongoing basis, because the plan for the business and the plan for the household change together every year.
Owner pay, retirement plans, the household portfolio and exit preparation, coordinated with your CPA and attorney.
If you want to offer a 401(k) to your team, we can serve as the plan's advisor and help it work for you as the owner as well.
See the 401(k) Plan Advisor serviceWe'll tell you on the first call where we can help, and where we can't.
Professional practices and closely held companies, from solo practices to companies with partners and staff. What they share is that the business is a large part of the owner's net worth, and the owner wants a plan for it.
Yes. Most of the work on entity structure, retirement plans and a sale happens in coordination with them, and we prefer it that way.
Ideally 5 to 10 years ahead, because some of the most useful moves need years to matter. If a sale is closer than that, the deal structure itself still leaves real room to plan.
30 minutes on the business, your timeline, and whether we're the right fit to help you plan both sides of it.
Prefer to text? (949) 259-5240