For Pharmacists
For many pharmacists, the steepest raises come in the first few years. After that, the gains come from decisions: which retirement plans you fill, how the loans from a Doctor of Pharmacy (PharmD) get paid, and what a per diem job is worth after tax. We make those decisions on purpose, every year.
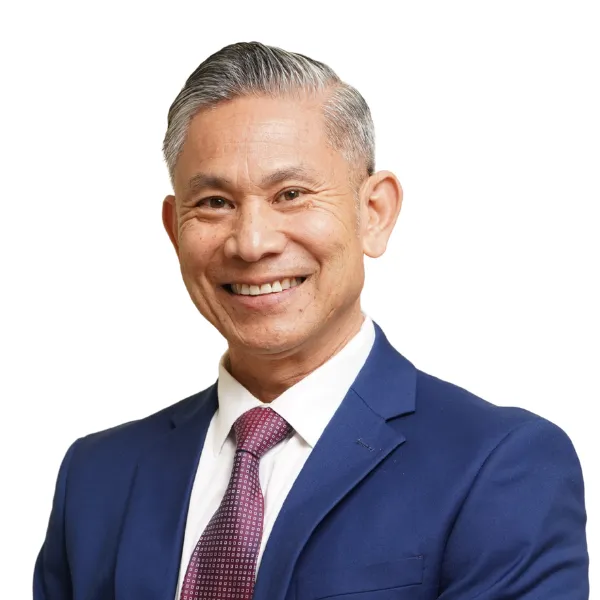
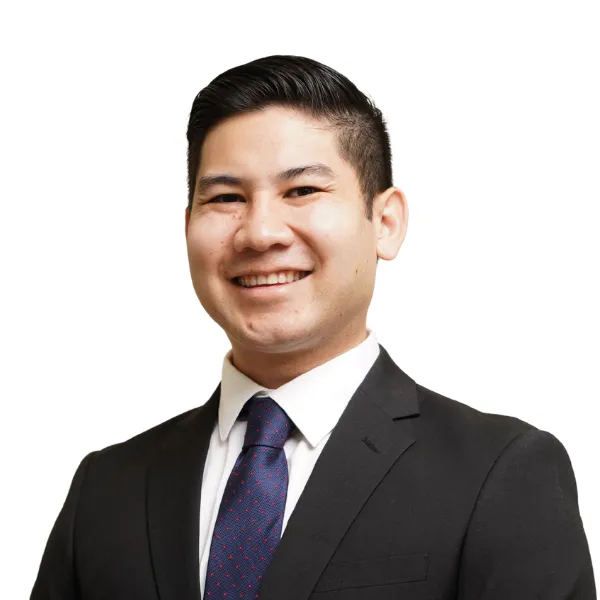
Nasar and Samee Aboubakare
Father and son. You work with both.
Prefer to text? (949) 259-5420
Often with a 403(b), a 457(b) and a nonprofit employer that counts toward loan forgiveness.
With a 401(k), stock purchase plans at larger employers, and loans that need a different strategy.
A second paycheck that shares retirement limits with the first, with no one coordinating the two.
Not a pharmacist? See all healthcare clinicians
When pay climbs fast, a missed deduction or an idle account gets covered by next year's raise. When pay levels off, each one stays missed.
Most pharmacists we meet have the pieces: a good salary, employer plans, a loan program. What's missing is someone putting them in order, so the loans, the taxes and the retirement accounts work together.
Good planning starts with one question: what do you want this career to pay for? Every other decision gets measured against that answer.
These come up in nearly every pharmacist's plan. Each has a right answer for your situation, and the default is usually the expensive one.
Many hospitals offer both. A 457(b) has its own $24,500 limit in 2026, separate from the 403(b). A nonprofit 457(b) also has rules about access and the employer's creditors, so it deserves a careful look before you fill it.
Public Service Loan Forgiveness (PSLF) counts payments made while you work for a qualifying nonprofit or government employer. Pre-tax retirement savings can lower an income-driven payment at the same time, so the two decisions belong together.
A base job and a per diem job share one $24,500 employee deferral limit in 2026, and neither payroll office sees the other. The withholding on a second job is also easy to get wrong.
Group disability through an employer often caps the benefit and ends when the job does. Knowing exactly what you have is the first step.
Timing
Illustrative example
A hospital pharmacist fills her 403(b) to the $24,500 limit for 2026 and assumes she is done. Her hospital also offers a 457(b), which has its own $24,500 limit.
If she defers $10,000 into the 457(b), her taxable income falls by $10,000. In a 24% federal bracket with California's 9.3% rate, that is about $3,300 less tax for the year. On an income-driven repayment plan, a lower income can also lower her loan payment, while her forgiveness count keeps running.
Hypothetical example for illustration only. Figures are simplified and rounded, and your results will differ. A nonprofit 457(b) has access and creditor rules to weigh first. This is general education, not individual tax or investment advice; we coordinate the details with your CPA.
Who you'll work with
Every client works with both of us. Nasar founded Sporos after building a private equity firm and then advising families at a big national firm. Samee trained as a chemical engineer at the University of Michigan and did equity research at a family office before joining the practice, so the analysis behind your plan is precise and the reasoning is written down.
For pharmacists, that pairing matters: one of us will run the loan and retirement math to the dollar, and the other has watched how these decisions play out across a career. We built the practice father and son because we intend to be here for the long run.
Every relationship starts with a 30-minute conversation about where you are and what you want this career to pay for.
Foundations $100, Tax Strategy $200 or Complex $300 a month, set by your situation, with no setup fee. Most clients start on Tax Strategy. You keep managing your own investments.
See pricingThe Complex plan, plus execution: we manage your investments and make the moves for you.
We'll tell you on the first call which path fits, including when neither does.
One flat monthly fee, set by your plan: Foundations $100, Tax Strategy $200 or Complex $300 a month. There's no setup fee. Your income and the size of your accounts don't change your price.
Yes. We meet virtually and work with clients in 15 states: AL, AZ, CA, CO, GA, IL, NJ, NV, NY, OH, OK, OR, PA, TX and WA. Our office is in Huntington Beach if you would rather meet in person.
Yes. Most of what we do for pharmacists touches taxes, so we coordinate directly with your CPA.
30 minutes on where you are, what you want this career to pay for, and whether we're the right fit to help you get there.
Prefer to text? (949) 259-5420