For CRNAs
As a Certified Registered Nurse Anesthetist (CRNA), you are often the highest earner in the building, and the offers keep coming: a group, a hospital, locums, independent contracting. Each one changes your taxes, your retirement plans and your insurance at once. We plan for that before you sign.
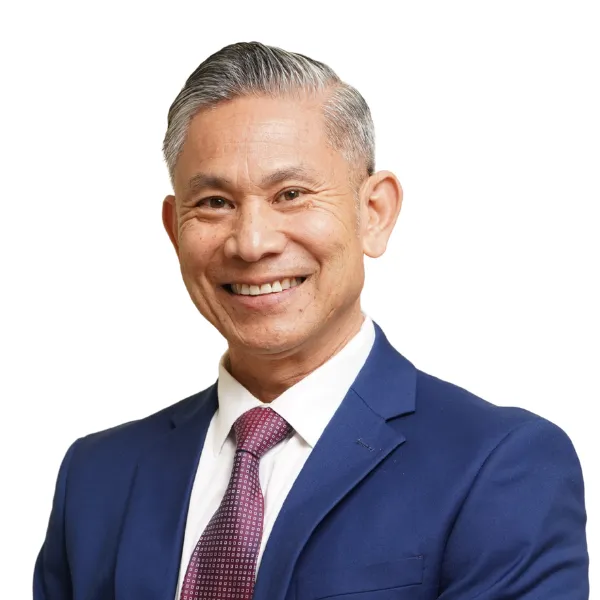
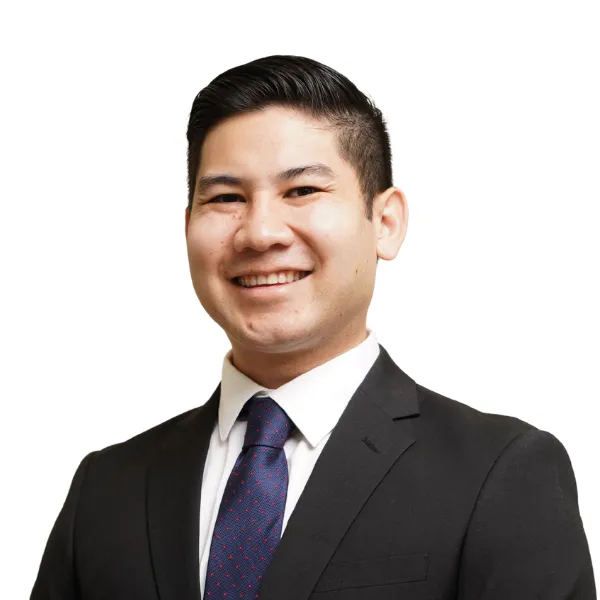
Nasar and Samee Aboubakare
Father and son. You work with both.
Prefer to text? (949) 259-5420
Employed by a hospital or an anesthesia group, often with a 403(b), a 457(b) and a disability policy you have never read.
Independent contractors and locums carrying their own retirement plan, malpractice and disability coverage.
A base job plus 1099 shifts, which is where most of the planning room hides.
Not a CRNA? See all healthcare clinicians
A 1099 offer usually arrives as one number: the hourly rate. The costs arrive later and one at a time: the employer half of payroll taxes, the retirement match you gave up, and the disability and malpractice coverage you now buy yourself.
Set up well, independent work opens retirement room a W-2 job never offers. Set up by default, a raise on paper can shrink once those costs land.
Good planning starts with the full comparison, done before you sign, measured against the way you want to work.
These come up in nearly every CRNA's plan. Each has a right answer for your situation, and the default is usually the expensive one.
Going 1099 changes how you are taxed, which retirement plans you can open and which insurance you carry. Whether an S corporation makes sense depends on your numbers, and we coordinate that call with your CPA.
1099 work is a small business, and that business can make its own contribution to a solo 401(k). With a base job and locums, both payroll offices share one $24,500 employee deferral limit in 2026, and neither sees the other.
Group disability often caps the benefit and ends with the job. As a 1099 CRNA you may also carry your own malpractice policy, and the choice between claims-made and occurrence coverage matters when you leave.
Public Service Loan Forgiveness (PSLF) depends on who signs your paycheck. Moving from a nonprofit hospital to a private group or 1099 work can stop the count, and nothing notifies you.
Timing
Illustrative example
A CRNA earns $210,000 as a hospital employee with a 4% 401(k) match. A group offers her $235,000 as a 1099 contractor. On paper, that is $25,000 more a year.
As a contractor she now pays the employer half of Social Security and Medicare tax, about $14,000 to $15,000 on this income. She gives up the $8,400 match, and her own disability and malpractice coverage costs her about $4,000 a year in this example. The $25,000 raise comes out roughly $2,000 short.
The offer can still be the right one. A solo 401(k) lets her business add its own contribution on top of her $24,500, room the hospital plan never offered. The point is to see the whole comparison before she signs.
Hypothetical example for illustration only. Figures are simplified and rounded, coverage costs are assumed, and your results will differ. This is general education, not individual tax or investment advice; we coordinate the details with your CPA.
Who you'll work with
Every client works with both of us. Nasar founded Sporos after building a private equity firm and then advising families at a big national firm. Samee trained as a chemical engineer at the University of Michigan and did equity research at a family office before joining the practice, so the analysis behind your plan is precise and the reasoning is written down.
For CRNAs, that pairing matters: one of us will model a 1099 offer to the dollar, and the other has watched how these decisions play out across a career. We built the practice father and son because we intend to be here for the long run.
Every relationship starts with a 30-minute conversation about where you are and how you want to work.
Foundations $100, Tax Strategy $200 or Complex $300 a month, set by your situation, with no setup fee. Most clients start on Tax Strategy. You keep managing your own investments.
See pricingThe Complex plan, plus execution: we manage your investments and make the moves for you.
We'll tell you on the first call which path fits, including when neither does.
One flat monthly fee, set by your plan: Foundations $100, Tax Strategy $200 or Complex $300 a month. There's no setup fee. Your income and the size of your accounts don't change your price.
Yes. We meet virtually and work with clients in 15 states: AL, AZ, CA, CO, GA, IL, NJ, NV, NY, OH, OK, OR, PA, TX and WA. Our office is in Huntington Beach if you would rather meet in person.
Yes. Most of what we do for CRNAs touches taxes, so we coordinate directly with your CPA. If you don't have one who works with 1099 clinicians, we can help you find one.
30 minutes on where you are, how you want to work, and whether we're the right fit to help you get there.
Prefer to text? (949) 259-5420